

Resources Categories
INDUSTRY FACT FILE · INSURANCE
Main Products and Services in Insurance and Reinsurance
What insurers and reinsurers offer, the systems behind each product and where those systems create cybersecurity and compliance exposure.
|
In this document 1. How insurers earn their money 2. Products by insurer type 3. Distribution and issuance 4. Claims and servicing 5. The systems behind the products 6. Product trends that change the attack surface 7. Mapping products to Codec Networks engagements |
1. How insurers earn their money
|
Revenue stream |
How it works |
Security relevance |
|
Premium income |
Premiums collected on life, general and health policies |
Issuance and payment systems must be available and accurate |
|
Investment income |
Returns on funds held to meet future claims |
Treasury and investment systems need strict access control |
|
Reinsurance commissions |
Commissions on business ceded to reinsurers |
Confidential data exchanged with reinsurers |
|
Claims efficiency |
Controlling fraud and leakage protects margins |
Claims systems are prime fraud targets |
2. Products by insurer type
|
Insurer type |
Main products |
Main services |
|
Life insurers |
Term, endowment, money-back, ULIPs, annuities, pensions, group life |
Underwriting, policy servicing, maturity and death claims, surrenders |
|
General insurers |
Motor, home, fire, marine, liability, travel, engineering, commercial |
Underwriting, surveys, claims and repairs through networks |
|
Health insurers |
Individual and family health, group health, critical illness, top-ups |
Cashless and reimbursement claims, wellness, network management |
|
Reinsurers |
Treaty and facultative reinsurance |
Risk transfer, catastrophe cover, technical support to insurers |
|
Specialised insurers |
Crop and agriculture insurance, export credit insurance |
Scheme administration and claims under government programmes |
3. Distribution and issuance
Policies are sold through agents and POSPs, banks and other corporate agents, brokers, web aggregators, insurer websites and apps, and insurance self-network platforms. Proposals often include medical, financial and identity data, and issuance increasingly happens digitally with e-KYC, video verification and online payment.
4. Claims and servicing
Claims flow through hospitals, garages, surveyors and third-party administrators (TPAs), with documents and medical records exchanged digitally. Policy servicing—address and nominee changes, payouts, surrenders and loans against policies—is a frequent target for social engineering and payout fraud.
|
Highest-risk moments Payout-detail changes, surrender requests and high-value claims are where fraud and cyber attacks converge. Strong verification, cooling periods and analytics break the most common fraud chains. |
5. The systems behind the products
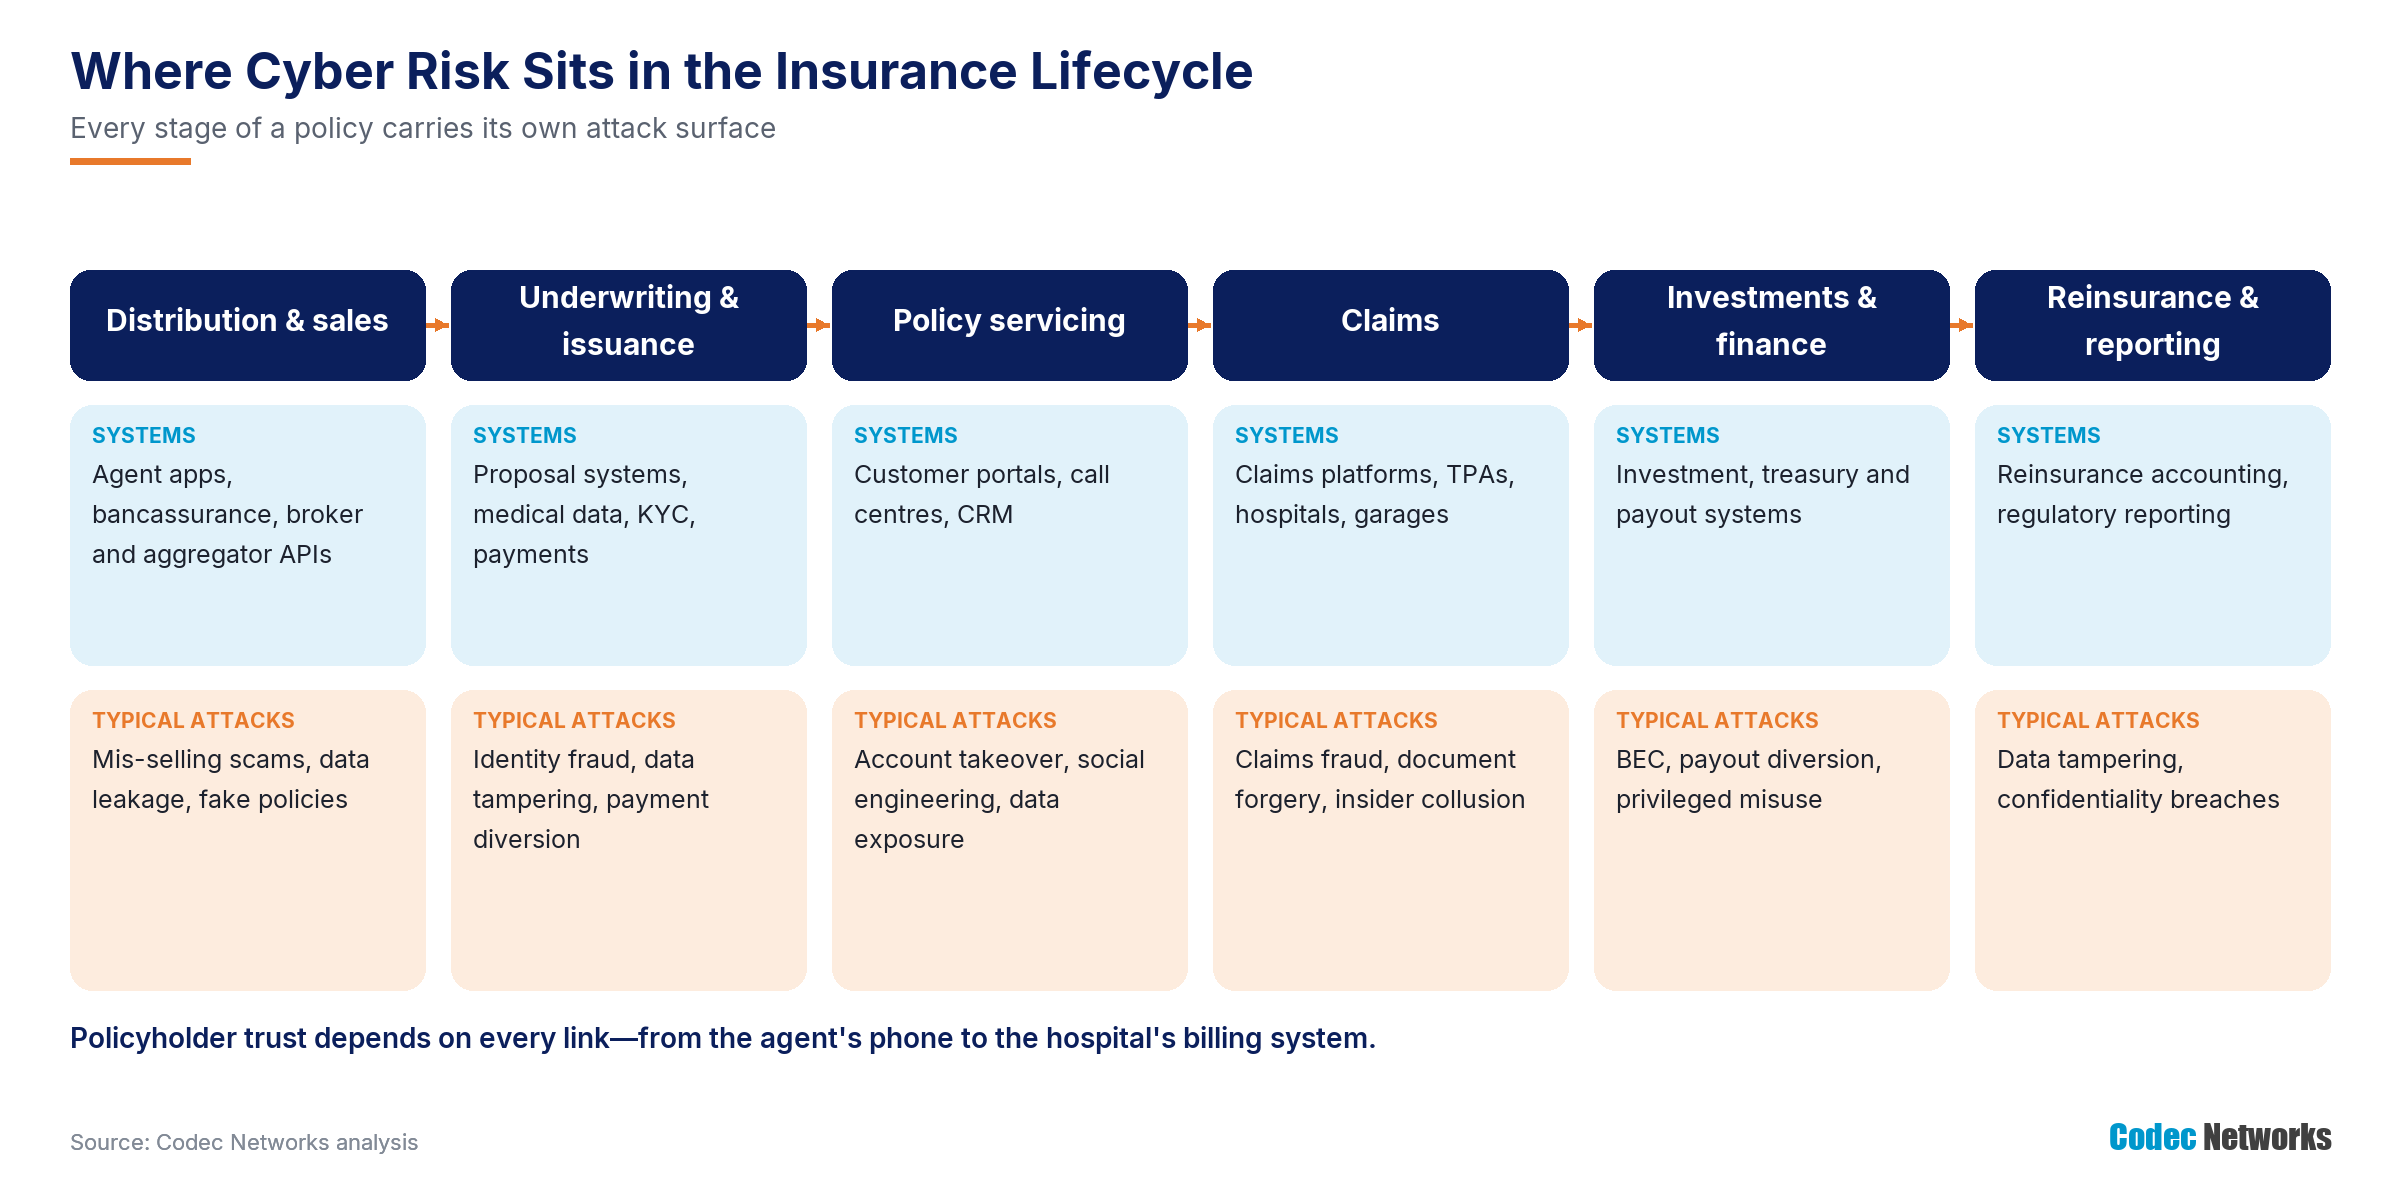
Figure 2: Where cyber risk sits in the insurance lifecycle.
|
Product / service |
Systems that deliver it |
Key cyber and compliance touchpoints |
|
Digital sales and issuance |
Websites, apps, agent and partner portals, payment gateways |
Application and API testing, six-monthly external PT |
|
Health claims |
Claims platforms, TPA portals, hospital interfaces |
Health data classification and encryption, partner assurance |
|
Motor and property claims |
Survey apps, garage networks, claims systems |
Partner access control, fraud analytics |
|
Policy servicing |
Customer portals, CRM, call centres |
Account security, payout-change controls, social-engineering resistance |
|
Core policy administration |
Legacy and modern policy systems, data warehouses |
Infrastructure VAPT, segmentation, backups |
|
Reinsurance |
Reinsurance accounting and data exchange |
Confidential data protection, email security |
6. Product trends that change the attack surface
|
Trend |
What is changing |
Security implication |
|
Digital-first distribution |
More sales through apps, platforms and partners |
API and partner security become critical |
|
Cashless and digital claims |
Faster claims with digital documents |
Document forgery and data leakage risks rise |
|
Cloud adoption |
Policy, claims and analytics workloads move to cloud |
IRDAI cloud requirements and shared responsibility |
|
AI in underwriting and claims |
AI models score risk and detect fraud |
Model manipulation and data-leakage risks |
|
Health data growth |
More medical and wellness data collected |
DPDP obligations and classification requirements |
7. Mapping products to Codec Networks engagements
|
If the insurer offers… |
Recommended starting engagement |
|
Digital sales and portals |
Application and API testing, six-monthly external PT |
|
Health insurance and cashless claims |
TPA and hospital interface assurance, health data protection programme |
|
Motor and property claims |
Claims platform testing, garage and surveyor access review, fraud analytics |
|
Life policies with surrenders and payouts |
Payout-change and surrender flow testing, brand monitoring |
|
Cloud-hosted platforms |
Review against IRDAI cloud requirements |
Talk to Codec Networks
|
Contact Codec Networks Pvt. Ltd. New Delhi: 507, 5th Floor, New Delhi House, Barakhamba Road, Connaught Place, New Delhi – 110001 Gurugram: 707, 7th Floor, Silverton Tower, Golf Course Extension Road, Sector 50, Gurugram – 122018, Haryana Landline: 011 430 496 96 | 011 437 522 99 Mobile: +91 99716 76124 | +91 88007 88220 | +91 88003 31124 Email: mktg@codecnetworks.com Web: www.codecnetworks.com |
Note: Descriptions are general and based on public information available as of October 2026. Insurance products are governed by IRDAI regulations.